

TETRA Technologies’s stock price has taken a beating over the past six months, shedding 26.7% of its value and falling to $6.15 per share. This may have investors wondering how to approach the situation.
Is now the time to buy TETRA Technologies, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think TETRA Technologies Will Underperform?
Despite the more favorable entry price, we’re cautious about TETRA Technologies. Here are three reasons we avoid TTI, plus one stock we’d rather own.
1. Long-Term Revenue Growth Shows Strong Momentum
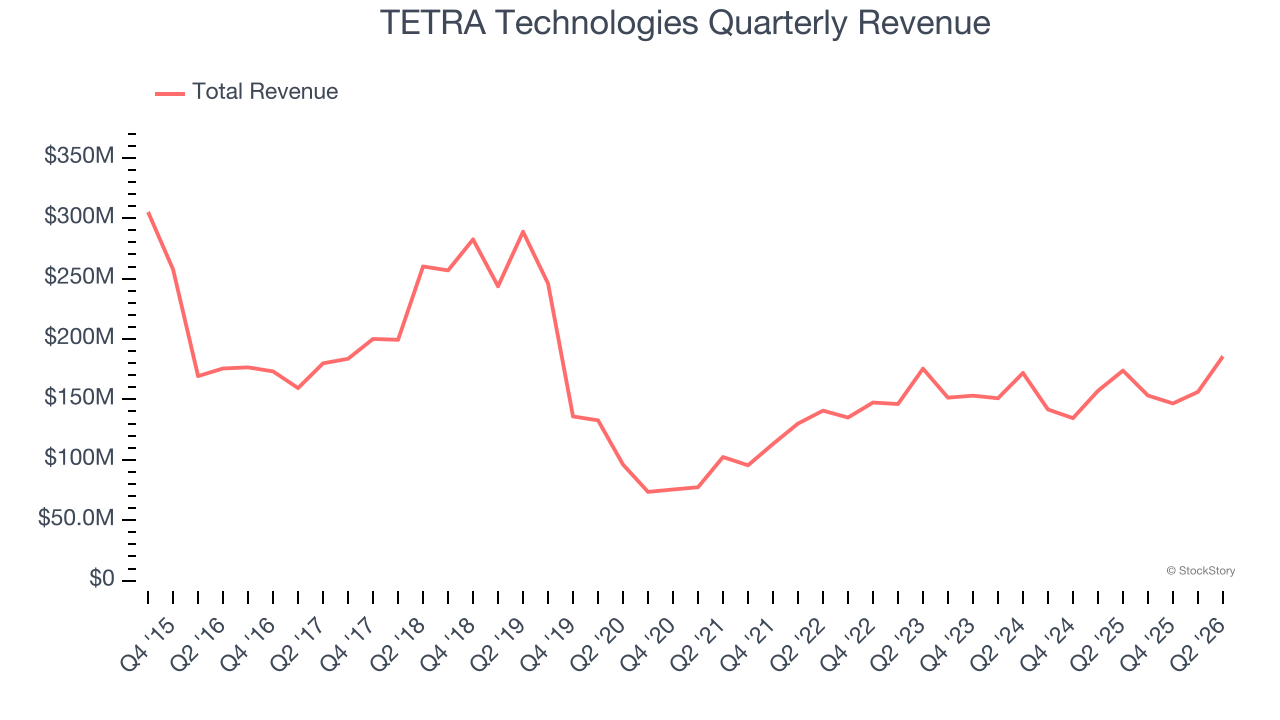
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Thankfully, TETRA Technologies’s 14.3% annualized revenue growth over the last five years was solid. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. Fewer Distribution Channels Limit Its Ceiling
In Energy, scale separates fragile single-asset producers from platform-style businesses that generate revenue across entire basins and infrastructure networks.
TETRA Technologies’s $641.8 million of revenue in the last year is pretty small for the industry, suggesting the company hasn’t hit a level of diversification where investors can sleep easy at night.
3. Low Gross Margin Reveals Weak Structural Profitability
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer (“rock” quality, takeaway, operating costs) or not.
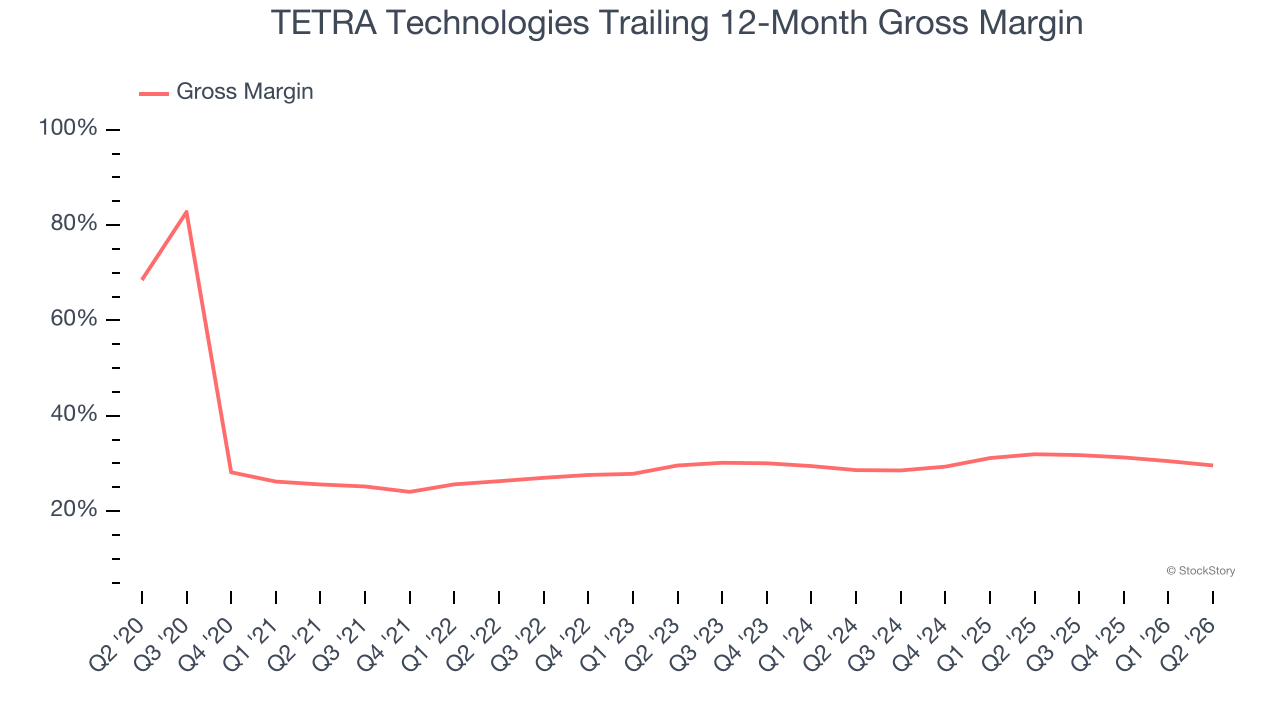
TETRA Technologies, which averaged 29.3% gross margin over the last five years, exhibited bottom-tier unit economics in the sector. It means the company will struggle at higher commodity prices than peers with better gross margins.
Final Judgment
We cheer for all companies serving everyday consumers, but in the case of TETRA Technologies, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 22.3× forward P/E (or $6.15 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think other companies feature superior fundamentals at the moment. We’d suggest looking at one of our all-time favorite software stocks.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.